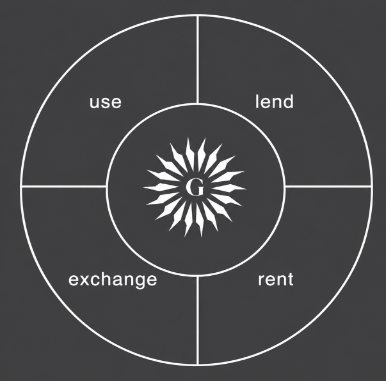
Personal use: where a member personally uses, free of charge, the enjoyment period attached to their shares, without receiving any rent or accommodation price, no tourist tax is to be collected in respect of that personal occupancy.
Rental: where the period is rented for consideration, the tourist tax is payable by the guest under the applicable rules and rates. The lessor must collect, declare and remit the tax to the competent authority, unless an online platform or payment intermediary is legally responsible for collecting and remitting it on the lessor’s behalf.
References: French General Local Authorities Code (CGCT), Arts. L. 2333-29 and L. 2333-33; Nice Côte d’Azur Metropolis tourist-tax procedures.